Key Takeaways
- In Queensland’s fast market, the terms of your offer can matter as much as the price, because sellers value certainty above almost everything.
- A cash offer wins on speed and certainty and can sometimes secure a lower price, but it ties up capital and gives up the benefit of leverage.
- A fully assessed mortgage pre-approval, not just pre-qualification, lets financed buyers compete with confidence and quicker settlement.
- Conditional offers protect you with finance and building clauses; unconditional offers look stronger to sellers but carry far more risk.
- Whether you buy with cash or pre-approval, the deposit, settlement terms and a buyer’s agent are what actually win the property.
The Queensland property market doesn’t wait for hesitation. In suburbs where open homes attract queues down the street, and contracts are signed within days of listing, the strength of your offer is just as critical as the price you are willing to pay. For many buyers, the anxiety isn’t about finding the right home; it’s about securing it before someone else does.
When you are competing against seasoned investors and decisive owner-occupiers, the terms of your finance can be the deciding factor. Sellers are looking for certainty. They want to know that when they sign a contract, the deal will settle without complications. This brings us to the two most powerful tools in a buyer’s arsenal: the unconditional cash offer and the pre-approved mortgage.
At Amassed, we see buyers grapple with this choice daily. Is cash always king? Or can a solid pre-approval strategy give you the same competitive edge without tying up all your liquidity? Understanding the nuances of these financial positions is the first step toward making a confident, successful purchase in a competitive market.
Understanding the Power of Cash Offers
In the world of real estate negotiation, a cash offer is often viewed as the gold standard. But it is important to clarify what “cash” means in this context. It doesn’t necessarily mean you have a suitcase full of banknotes; it means you have the liquid funds available in your bank account to purchase the property outright without needing a loan from a bank.
The Advantages of Cash
The primary benefit of a cash offer is speed and certainty. Because you aren’t waiting for a bank to value the property or approve your loan application, you can usually offer a shorter settlement period. For a seller who has already bought another house or needs to move quickly, this is incredibly attractive.
Furthermore, cash offers are typically unconditional regarding finance. This removes the risk of the sale falling through due to a lender declining the mortgage,a major stress point for vendors. Consequently, sellers may sometimes accept a lower cash offer over a higher offer that is subject to finance, simply for the peace of mind.
The Disadvantages of Cash
However, buying with cash isn’t without its downsides. The most obvious is the opportunity cost. By tying up a large amount of capital in a single illiquid asset, you lose the ability to use those funds elsewhere.
Additionally, using all your cash reduces your financial buffer for renovations, repairs, or unexpected life expenses. For investors, paying cash also eliminates the benefits of leverage, using the bank’s money to amplify your potential returns, which is a cornerstone of many property investment strategies.
The Edge of Pre-Approval in a Competitive Market
For the vast majority of buyers, paying cash isn’t an option. This is where a robust mortgage pre-approval becomes essential. It is the bridge between needing finance and presenting as a serious, “ready-to-go” buyer.
What is Mortgage Pre-Approval?
It is crucial to distinguish between a simple “pre-qualification” and a formal “pre-approval.” Pre-qualification is often just an estimate based on what you tell a lender. Pre-approval, however, involves a lender verifying your income, credit history, and debts to provide a formal indication of how much they are willing to lend you.
Benefits in a Competitive Market
In a hot market like Brisbane or the Sunshine Coast, a pre-approval letter signals to agents and vendors that you have done your homework. It shows you are financially vetted and capable of closing the deal.
While it isn’t quite as risk-free as cash in the eyes of a seller, a fully assessed pre-approval allows you to make offers with confidence. You know your budget ceiling, preventing the heartbreak of falling in love with a home you can’t afford. It also speeds up the formal approval process once your offer is accepted, allowing for quicker settlement terms that can rival cash buyers.
Cash vs. Pre-Approval: Which is Right for You?
Deciding between leveraging cash and relying on financing depends on your financial goals and risk tolerance.
Factors to Consider
- Market Conditions: In an overheating market where properties sell in days, the speed of cash is powerful. However, a pre-approved buyer who acts quickly can still compete effectively.
- Liquidity Needs: Do you need cash on hand for business or other investments? If so, a mortgage might be safer, keeping your liquid assets available.
- Property Condition: Banks can be fussy about lending on properties that need significant repairs. If you are buying a “fixer-upper,” a cash offer avoids the risk of the bank rejecting the security.
Scenarios for Success
If you are a retiree looking to downsize and want a stress-free transaction, cash is often the best route. Conversely, if you are a young professional or an investor looking to build a portfolio, using a pre-approval to leverage the bank’s money is generally the smarter long-term wealth strategy.
Cash Offer vs Mortgage Pre-Approval: Side by Side
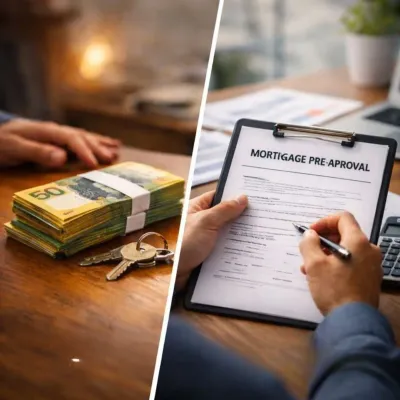
A quick cash offer vs mortgage pre-approval comparison makes the trade-offs clear. Cash leads on speed and seller certainty, while pre-approval keeps your capital working and preserves the power of leverage. Neither is universally “better”; the right choice depends on your goals, timeline and how competitive the specific property is.
| Factor | Cash Offer | Mortgage Pre-Approval |
|---|---|---|
| Speed to settle | Fastest, no lender steps | Fast once formally assessed |
| Seller certainty | Highest, no finance clause | High with full pre-approval |
| Leverage | None, full capital used | Uses the bank’s money |
| Liquidity kept | Low, capital tied up | Higher, cash stays available |
| Best suited to | Downsizers, fixer-uppers | Investors, owner-occupiers |
The takeaway is simple: a financed buyer who is fully pre-approved, ready to move, and flexible on settlement can compete with many cash buyers, especially when guided by a strong offer strategy.
It also helps to understand why sellers weigh these factors so heavily. Every vendor is really buying two things when they accept an offer: the price, and the probability that the deal actually completes. A cash offer scores nearly full marks on that second measure, which is why a slightly lower cash figure can still beat a higher financed one. The good news for financed buyers is that probability of completion is something you can influence. By removing avoidable conditions, shortening timeframes, and demonstrating that your lender has already done the heavy lifting, you close much of the gap that cash would otherwise open.
Conditional vs Unconditional Offers in Queensland
Understanding conditional and unconditional offers is essential before you sign anything in Queensland. A conditional offer includes clauses that must be satisfied, most commonly subject to finance, building and pest, or the sale of another property. These clauses protect you: if finance falls through or the inspection uncovers a serious defect, you can withdraw within the agreed terms. An unconditional offer removes those safety nets, which is why sellers love it and why it carries real risk for the buyer.
Queensland contracts also include a statutory cooling-off period on most residential sales, and the standard REIQ contract sets out how finance and inspection conditions work. The official Queensland Government guidance explains these rights before you commit. For most financed buyers, the smart play is a tightly worded conditional offer with short, realistic timeframes, which reads almost as strongly as an unconditional one while still protecting you. This is exactly the kind of structuring a buyer’s agency service manages on your behalf.
How to Make Your Offer Stand Out Without Paying Cash
You do not need cash to present the strongest offer in the room. The levers that matter most to a seller are certainty and convenience, and financed buyers can pull several of them. Come in with a full pre-approval, a healthy deposit, and a settlement date that suits the vendor rather than just you. Keep your conditions few and your timeframes short, so your offer reads as low-risk.
The deposit you need also shapes how your offer is perceived, since a larger deposit signals commitment and financial strength. Beyond the numbers, presentation and timing win deals: a clean contract, a prompt response, and a clear line of communication reassure the seller. This is where sharp negotiation strategy separates the winning offer from the one that just misses, turning a financed position into a genuinely competitive one.
There are practical touches that cost nothing but move you up the seller’s list. Offering a settlement date that matches the vendor’s plans, rather than forcing your own timeline, removes friction. Being contactable and quick to sign shows you are serious and organised. Where it suits your situation, a slightly larger deposit at exchange gives the seller extra confidence that you will complete. None of these tactics require cash reserves; they require preparation and a clear head. Buyers who line these elements up in advance rarely have to win on price alone, because their offer already reads as the safe pair of hands the vendor is looking for.
Finding Leading Buyers Agents in Key Sunshine Coast Regions
Even with your finances sorted, navigating the local market requires on-the-ground expertise. A skilled buyer’s agent does more than just bid; they help you identify value, assess risks like flood zones, and manage negotiations to ensure you don’t overpay.
Finding the right representation is critical. You might be searching for the Best buyers agent Brisbane has available to help you secure a family home in a blue-chip suburb. Perhaps you need a Leading buyers agent Gold Coast based who understands the nuances of the beachfront market versus the hinterland. Or, you might need a Leading buyers agent Sunshine Coast specialist to help you compete for a holiday investment in Noosa.
Regardless of the location, the goal remains the same: to have an independent expert in your corner. At Amassed, we believe that combining your financial strategy, whether cash or pre-approval, with expert local advocacy is the surest way to secure the right property at the right price.
Frequently Asked Questions
Best buyers agent Sunshine Coast
When looking for the best representation on the Sunshine Coast, look for an agent who prioritises education over sales pressure. The “best” agent isn’t just the one who closes the deal fastest; it’s the one who ensures you are buying a high-quality asset that aligns with your long-term wealth goals, rather than just shifting stock.
Leading buyers agent Gold Coast
A leading agent on the Gold Coast should have deep networks that grant you access to off-market opportunities. In competitive coastal markets, many of the best properties never hit the public listing portals. An agent with strong relationships can get you through the door before the general public, giving you a distinct advantage.
Does pre-approval guarantee I will get the loan?
No, pre-approval is not an absolute guarantee. It is conditional on the property valuation and your financial situation remaining unchanged. If you buy a property that the bank deems risky, or if you lose your job before settlement, the loan can still be declined.
Can I offer less money if I am paying cash?
Often, yes. Because cash offers come with fewer conditions and a faster settlement, sellers perceive them as lower risk. You may be able to negotiate a lower purchase price compared to a buyer whose offer is subject to finance, as the seller is “paying” for the certainty you provide.
How long does a pre-approval last?
Typically, a pre-approval is valid for 3 to 6 months, depending on the lender. If you haven’t bought a property within that timeframe, you may need to resubmit updated financial documents (like recent payslips) to renew the approval.
Is a cash offer better than mortgage pre-approval?
Not always. A cash offer is stronger on speed and certainty, so it can win in a fast-moving sale or on a property banks are wary of lending against. But a fully assessed pre-approval lets you keep leverage and liquidity, and it competes well when your terms are tight. Movements in the RBA cash rate also affect borrowing power, so timing matters.
How much deposit do I need for mortgage pre-approval?
Most lenders look for a 20 percent deposit to avoid lenders mortgage insurance, though smaller deposits are possible at higher cost. A larger deposit strengthens both your pre-approval and how sellers view your offer. See our client results for how deposit and terms shape outcomes, and the ASIC MoneySmart home loan guide for the finance detail.
What is the difference between conditional and unconditional offers?
A conditional offer includes clauses such as subject to finance or building and pest, letting you withdraw if a condition is not met. An unconditional offer removes those protections and binds you to the purchase, which sellers prefer but which is far riskier for buyers. Check your rights under the Queensland property law before going unconditional.
Making the Right Choice with Amassed
Whether you enter the market with cash in hand or a pre-approval letter in your pocket, the key to winning isn’t just the money; it’s the strategy behind it. Real estate is a long-term game, and the decisions you make today regarding finance and asset selection will impact your wealth for years to come.
Buying property shouldn’t be a guessing game. By understanding the strength of your financial position and partnering with independent experts, you can move from uncertainty to confidence. If you are ready to secure your future in the Queensland property market, we are here to help you navigate every step of the journey.
Ready to buy with confidence? Request a free consultation with Amassed today.
Resources
Elijah Turkovic
Elijah Turkovic is the founder of Amassed and a leading buyer’s advocate known for helping clients secure high-value properties across Queensland. With a data-driven approach, sharp negotiation skills, and deep market insight, Elijah guides buyers toward smarter decisions and stronger long-term outcomes.