Key Takeaways
- Data-driven property investment replaces hype and gut feel with evidence: rental yield, capital growth, vacancy rates and supply data guide every decision.
- The strongest strategies are chosen deliberately, whether that is capital growth, rental yield, a balanced approach, or rentvesting to match your goals.
- Researching an investment property before you buy means analysing the suburb and the market around it, not just the house itself.
- Chasing a cheap price or an “investment-grade” label without data is how investors overpay and stall. Fundamentals matter more than buzzwords.
- The same numbers that pick a winner also flag the mistakes to avoid, from oversupplied markets to emotional purchases and miscalculated costs.
Building wealth through property is no longer about following market hype or trusting instinct. Successful investors now treat every purchase as an evidence problem, using data-driven property investment to assess rental yield, capital growth potential, vacancy rates and long-term market performance before they commit a dollar. With Australia’s residential property worth $12.3 trillion according to the Australian Bureau of Statistics, the cost of a poorly researched decision has never been higher. This guide sets out the strategies, the research process and the exact numbers that separate a strong asset from an expensive mistake.
What Is Data-Driven Property Investment?
Data-driven property investment is a strategy that prioritises factual analysis over emotional intuition. Instead of falling for a property’s presentation or renovation potential, the investor looks at the numbers first. Traditionally, many buyers purchased in areas they felt were up and coming, or simply close to where they lived. That approach leaves too much of your financial future to chance.
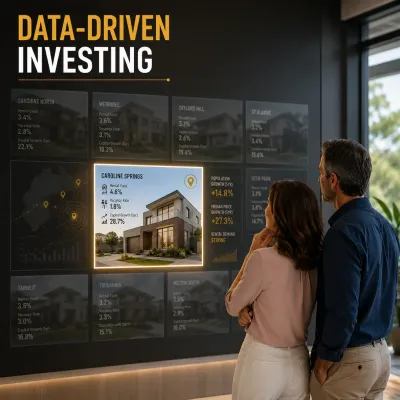
A data-led approach flips the script. It analyses comprehensive datasets, including vacancy rates, historical capital growth, rental yield trends, infrastructure pipelines and population shifts, to identify high-performing assets before the broader market catches on. The primary benefit is risk mitigation. When you understand the numbers, you can act with confidence rather than hope, which is the foundation of smart property investment. This is also the essence of data driven suburb selection: letting the evidence, rather than a hot tip, decide where your money goes. In short, data driven property investment treats each purchase as a research problem to be solved, not a feeling to be acted on. Working with the Amassed team means every recommendation is built on that evidence first.
The Best Property Investment Strategies for Long-Term Wealth
Successful property investment strategies are built around clear financial goals, reliable market data and long-term decision-making. Different strategies produce different outcomes, so the right approach depends on your risk tolerance, borrowing capacity, cash flow needs and wealth objectives. Investors who follow a structured method are usually better positioned to manage market shifts and avoid emotionally driven decisions.
Capital growth strategy
A capital growth strategy targets properties in locations with strong long-term appreciation potential. These assets may not deliver the highest rental yield initially, but they are chosen for their ability to increase in value over time. Investors using this approach favour tightly held suburbs, areas with infrastructure upgrades, strong owner-occupier demand and population growth. Long-term growth is usually tied to scarcity and sustained demand, not simply a low purchase price.
Rental yield strategy
A rental yield strategy prioritises cash flow and consistent rental income. It suits investors looking to improve serviceability or build a stable income stream, and high-yield properties are often found in affordable growth corridors and suburbs near universities, hospitals or transport hubs. Yield should never be analysed in isolation, however. For the full trade-off between income and growth, our guide to growth versus cash flow breaks the decision down in detail.
Balanced, rentvesting and percentage growth approaches
Many experienced investors aim for a balanced strategy that combines moderate yield with strong long-term growth, targeting established suburbs with diverse economic drivers while avoiding oversupplied apartment markets. Rentvesting is another practical model: you rent where you want to live and buy an investment property in a more affordable, higher-growth area. A final discipline is to prioritise percentage growth over dollar gains. A $50,000 rise on a $500,000 property is a 10 per cent return, while the same gain on a $1 million property is only five per cent, so affordable markets with strong growth rates often build equity faster. If you are still weighing the asset type itself, our comparison of houses or units applies the same evidence-first lens to that choice.
How to Research an Investment Property Before You Buy
Strong decisions start with research, not assumptions. Before purchasing, investors should analyse suburb performance, rental demand, infrastructure growth and long-term market trends to confirm a property aligns with their goals. Many buyers focus heavily on the property itself while overlooking the market around it, yet even a well-presented home can underperform in an area with weak demand or high vacancy. This is exactly why property investment research matters, and Australia’s Moneysmart service is a useful independent starting point for understanding the risks before you buy.
Analysing suburb growth trends
Understanding suburb growth trends helps identify locations with stronger long-term potential. Review median price growth over time, days on market, auction clearance rates, owner-occupier demand and future housing supply. Consistent growth is usually supported by strong local fundamentals such as improving infrastructure and employment access, rather than short-term speculation.
Understanding vacancy rates and rental demand
Vacancy rates are one of the clearest indicators of rental demand. A low vacancy rate generally means more tenants than available supply, which supports stronger returns and reduces the risk of a property sitting empty. Assess vacancy alongside weekly rental trends, tenant demographics, local employment hubs and new supply. A property with strong advertised returns but weak tenant demand can quickly become difficult to lease.
Reviewing supply, infrastructure and population growth
Supply is the enemy of capital growth, so check local council development applications before you buy. A suburb with heavy approvals for new units may see prices stagnate, while one with strong demand and limited new building is often safer. New transport links, schools, hospitals and employment hubs lift demand over time, so investors who read infrastructure pipelines early can act before wider competition arrives.
Which Data Points and Digital Tools Actually Matter?
To invest well you need to know which numbers count. A property can look like a bargain on price alone while hidden costs or weak growth potential quietly turn it into a liability.
The key data points to scrutinise
Focus on purchase price versus comparable sales, rental yield as a percentage of value, vacancy rates, operating expenses such as council rates, insurance and management fees, and days on market as a read on buyer or seller power. Analysed together, these figures reveal the true net return rather than the headline one.
The property data platforms professionals use
Serious buyers verify everything with data. Industry platforms built on CoreLogic property records provide sales history, ownership details and comparable sales, which is invaluable for estimating value from hard evidence rather than an agent’s price guide. Suburb-level tools add rental yields, vacancy rates and demographic shifts to help locate emerging pockets of value. Interpreting that data is where the advantage lies, which is why a professional buyers agency service pairs enterprise data with on-the-ground insight.
Council mapping for flood, zoning and overlays
Government interactive mapping is essential for due diligence. Council planning portals let you check flood overlays, zoning, easements and infrastructure plans before you make an offer, which can prevent expensive surprises after settlement. A structured feasibility study brings these checks together so the physical and regulatory risks of a site are understood upfront.
Capital Growth vs Rental Yield: Which Matters More?
Capital growth measures how much a property rises in value over time, while rental yield measures the income it generates relative to price. Neither is universally better. Capital growth suits investors focused on long-term wealth, and is commonly driven by infrastructure investment, population growth, owner-occupier demand and limited supply. Rental yield matters more when cash flow and serviceability are the priority, which is common for first-time investors or those building multiple-property portfolios.
Experienced investors rarely chase one in isolation. They look for a sustainable balance of income and appreciation, testing vacancy rates alongside capital growth history and avoiding oversupplied markets. The question of capital growth vs rental yield is best answered by your own strategy and financial position, not by a rule of thumb.
Should You Chase an ‘Investment-Grade’ Property?
The term investment grade property is used constantly in real estate to describe assets that theoretically offer strong growth and consistent demand. The label can be misleading. Media top-ten lists create a frenzy where buyers believe only a tiny fraction of properties are worth owning, and pay a premium to fit the popular mould. A property that suits a high-income earner chasing growth can be completely wrong for someone who needs positive cash flow.
What the numbers really say about investors
A dose of perspective helps. According to the latest Australian Taxation Office taxation statistics, there are more than 2.2 million property investors in Australia, and over 71 per cent own just one investment property. Very few investors ever build large portfolios, which tells you that sustainable strategy, not chasing a perfect asset, is what actually works. Success typically moves through three stages: accumulation, where you grow your asset base, transition, where you pay down debt, and living off the income your portfolio produces.
A related trap is buying purely to reduce tax. Some investors purchase a property that loses money every week just to claim a deduction, treating a short-term funding tactic as a wealth strategy. Data reframes the question. A poor-performing asset is still a poor asset, regardless of the tax outcome, and financial fluency, understanding good debt from bad and stress-testing repayments against higher rates, protects you far better than any label. The best property is the one whose numbers support your stage of wealth, not the one that photographs well or fits a headline.
The waterfront warning
Premium waterfront homes show the danger of chasing prestige over fundamentals. They often carry strict zoning rules, expensive flood and storm insurance, uncertain shoreline ownership, harsh weather wear and tightening short-term rental regulations. These hidden costs can erode returns, which is why the label matters far less than the maths behind the specific property.
Common Property Investment Mistakes Data Helps You Avoid
Most mistakes happen when buyers rely on emotion, assumptions or short-term hype instead of objective analysis. A data-driven approach identifies risks earlier and grounds decisions in evidence, and the most common property investment mistakes are surprisingly avoidable.
Chasing cheap prices and ignoring supply
A lower purchase price does not automatically mean a better investment. Properties in weaker locations can experience slower growth, longer vacancies and softer tenant demand. Supply matters just as much: suburbs with heavy new development, particularly apartment-dense markets, can struggle to hold price growth, so always weigh upcoming developments and vacancy trends. Single-industry towns carry a similar risk. A location that depends on one mine, factory or employer can look cheap and high-yielding right up until that employer scales back, at which point prices and rents can fall together. Diversified local economies, proximity to transport and multiple employment hubs are what keep demand resilient through a downturn, and those are exactly the fundamentals a data-led screen is built to surface before you commit.
Emotion, costs and skipping due diligence
Emotional decisions and fear of missing out lead buyers to overpay, so anchor every offer to comparable sales and long-term growth data. Costs are the other trap. Budget for stamp duty, legal fees, inspections, council rates, insurance, land tax and a cash buffer for vacancy or repairs. Never skip a professional building and pest inspection either, and use a thorough due diligence checklist so structural or legal issues surface before contracts, not after.
Getting the structure, finance and tax settings right
Ownership structure and finance shape your returns and are hard to change later, so seek advice on whether to buy as an individual, in a trust or through another entity, and secure loan pre-approval before you make offers. Tax settings are shifting too. Under the tax reform legislated in 2026, negative gearing for residential property will be limited to new builds from 1 July 2027, with properties held before the 12 May 2026 announcement grandfathered, and the 50 per cent capital gains tax discount is being replaced with indexation and a 30 per cent minimum tax rate on gains after that date. Confirm your position with a registered tax professional, and our investment property tax guide explains the current settings in plain terms.
How a Structured, Data-Backed Process Works
Consistency is what turns good data into a portfolio that lasts. A structured, evidence-based process removes the emotional rollercoaster from investing, because you stop wondering “what if” and start knowing “why”. The goal is to make every purchase a repeatable decision rather than a one-off gamble.
A repeatable five-step system
A robust system moves through five stages. First, strategy formulation, defining clear goals based on your financial capacity. Second, market research, using macro and micro data to select the right location. Third, property identification, shortlisting assets that meet strict criteria. Fourth, due diligence, rigorously checking legal, structural and pest issues. Fifth, negotiation, using data to secure the property on fair terms. A short strategy consultation is often where that system starts, translating your position into a clear brief.
Why local knowledge still beats raw data
Data tells you where to look, but local knowledge tells you what the numbers cannot. A screen might rank two streets equally while one sits beside a future high-density zone and the other does not. This is why experienced Gold Coast buyers agents pair enterprise datasets with on-the-ground insight, for example using interactive council mapping to spot an undervalued pocket zoned for future density. That same discipline, applied consistently, is how investors build a property portfolio rather than a single lucky purchase.
The role of a buyers agent
A buyers agent pulls these threads together. Acting only for the purchaser, a good agent interprets the data, filters unsuitable stock and negotiates from evidence rather than emotion. You can see the outcomes on our client results page, and when you are ready to test a specific property or suburb against the numbers, you can request a free consultation to put the process to work on your own search.
Frequently Asked Questions
What is a good rental yield for an investment property in Australia?
A good rental yield depends on property type, location and strategy, but many Australian investors consider gross yields between 4 and 6 per cent relatively strong. Yield should always be assessed alongside vacancy rates, operating costs and long-term capital growth potential rather than as a standalone number, because a high headline yield in a weak-demand area can still be a poor investment.
How do investors research property investment opportunities?
Investors research property investment opportunities by analysing suburb growth trends, rental demand, vacancy rates, infrastructure projects, historical sales data and local supply levels. A data-driven property investment strategy combines these datasets so buyers can identify stronger long-term opportunities while reducing the risk of overpaying or buying in an underperforming market.
What is an investment-grade property?
An investment grade property is generally described as an established asset in a high-demand location with strong capital growth history and consistent rental demand. In practice the label is subjective and often overused, so it should never replace your own analysis. The right property is the one whose data supports your specific strategy and stage of wealth, not the one carrying the most marketing.
What are the high growth suburbs in Australia for 2026?
The high growth suburbs australia 2026 investors should watch share common traits rather than a fixed postcode list: population growth, infrastructure investment, tight vacancy rates, limited new supply and diverse local employment. Because conditions change quarter to quarter, the reliable method is to screen suburbs against those fundamentals using current data rather than relying on last year’s hotspot articles.
Can a buyers agent help me find off-market properties?
Yes. Buyers agents maintain extensive networks with sales agents and private sellers, which gives them access to silent listings and off-market properties that are never advertised publicly. This reduces competition and can protect your price, and it pairs naturally with the data-driven filtering a good agent applies before recommending any asset.
Why is data important in property investment?
Data removes emotion from the decision. By analysing facts such as rental yields, historical growth and vacancy rates, investors can identify assets with genuine financial merit and avoid properties that look appealing but perform poorly. Evidence-based decisions reduce risk and improve the odds of strong long-term returns across changing market conditions.
Resources
- Australian Bureau of Statistics, Total value of dwellings reaches $12 trillion
- Moneysmart, Buying an investment property
- Moneysmart, Property investment
- Australian Taxation Office, Taxation statistics
- Australian Taxation Office, Reforming negative gearing and capital gains tax
- CoreLogic, Australian housing data
- Reserve Bank of Australia, Housing and mortgage markets
Elijah Turkovic
Elijah Turkovic is the founder of Amassed and a leading buyer’s advocate known for helping clients secure high-value properties across Queensland. With a data-driven approach, sharp negotiation skills, and deep market insight, Elijah guides buyers toward smarter decisions and stronger long-term outcomes.