
Key Takeaways
A practical guide to capital growth versus cash flow, how to sequence property purchases, and how renovation can manufacture both.
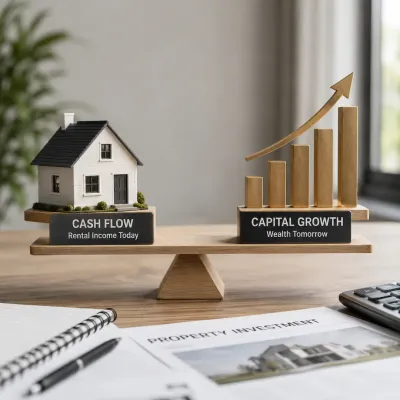
- Capital growth builds the equity that funds your next purchase, while cash flow keeps the portfolio affordable to hold.
- It is not an either-or choice; it is a sequencing decision that changes as your portfolio matures.
- Early investors usually prioritise growth to build equity, then shift toward cash flow to service debt later.
- A well-planned renovation can lift both value and rent, but overcapitalising quietly destroys the gain.
- The right balance always depends on your borrowing capacity, timeframe and long-term goals.
Many property investors face the same dilemma at the start of their journey. Should you chase high rental returns now, or focus on long-term value increases? That single choice shapes how quickly you can scale a portfolio and reach financial freedom. The debate is ongoing: some insist cash in the bank is king, others that only capital gains build real wealth.
The truth is that a successful strategy needs a clear understanding of how both elements work over time, and how to sequence them. This guide explains the difference, shows you when to prioritise each, and covers how renovation can manufacture both at once. As the Amassed buyer’s agents consistently find, the right answer depends entirely on your current financial position and where you want to end up.
What Is the Difference Between Capital Growth and Cash Flow?
They are the two engines of property wealth, and they do very different jobs.
What is capital growth
Capital growth is the increase in a property’s market value over time. Buy a house for $600,000 and watch it reach $800,000 over five years, and you have created $200,000 in capital growth. That gain is not taxed until you sell, so it compounds quietly in the background, and most successful investors rely on this appreciation to fund their future purchases.
What is cash flow
Cash flow is the rental income left after paying every property expense: mortgage repayments, management fees, council rates, insurance and maintenance. When rent exceeds those costs you have positive cash flow; when costs win, it is negative. This is the number that dictates how comfortably you can hold the property month to month.
Why both matter for wealth building
A resilient portfolio needs both. Value appreciation builds your net worth and the equity you need to buy again, while rental income keeps you solvent through rate rises, vacancies and life’s surprises. Focusing on only one leaves your journey either stalled or exposed, a balance the guidance on ASIC MoneySmart reinforces for any new investor. Think of growth as the wealth engine and cash flow as the fuel that keeps it running: a powerful engine with no fuel stops, and plenty of fuel with no engine goes nowhere. The investors who last are the ones who respect both from the very first purchase.
How Does Capital Growth Build Wealth?
By turning one property into the deposit for the next. When your property rises in value, you build usable equity, and banks generally let you borrow against up to 80 per cent of that value. You can use it as the deposit for your next purchase without saving a fresh one from your salary.
One property funds the second, two fund the third, and that compounding is how everyday Australians build significant asset bases. Our guide to building a property portfolio walks through the mechanics, and long-run CoreLogic data shows Australian dwelling values have risen roughly 6 to 7 per cent a year over recent decades, with forecasters tipping continued national growth into 2026.
Equity and borrowing capacity
Equity is the difference between your property’s value and the debt against it, and it is the quiet driver of every growing portfolio. As values rise, that usable equity can be released and recycled into the next deposit, so your existing assets do the saving for you. The compounding is powerful: a single property appreciating at seven per cent doubles in value in roughly a decade, and two or three doing the same create a snowball that salary savings alone could never match. The discipline is to release equity within a sensible buffer rather than borrowing to the very limit, because the same leverage that accelerates growth also magnifies risk if the market pauses.
What drives strong capital growth
Not all suburbs grow at the same pace, and specific ingredients push prices higher. Population growth and high migration create immediate housing demand. Infrastructure spending on transport, hospitals and schools draws new residents and businesses. Diverse employment near major hubs attracts higher-income earners and adds stability. And restricted supply, through tight zoning or limited land, concentrates price pressure whenever demand rises.
The strongest growth locations show several of these at once. The real skill is spotting them before the crowd does, when a rezoning is proposed rather than approved, or an infrastructure project is funded rather than finished. By the time a suburb tops every hotspot list, much of the growth is already priced in, which is why serious investors track council plans and migration data rather than magazine rankings.
A tale of two properties
Consider two choices. Property A is an inner-city house bought for $700,000 on a modest three per cent yield. Property B is a regional unit bought for $400,000 on a strong seven per cent yield. Ten years on, if Property A grows at seven per cent a year it passes $1.3 million, while Property B growing at two per cent reaches roughly $487,000. Property A’s owner has built more than $600,000 in equity; Property B’s owner enjoyed better weekly income but far less overall wealth. Neither choice is wrong, but they build wealth in completely different ways, and understanding that gap is the foundation of a sound strategy.
Why Does Cash Flow Sustain Your Portfolio?
Because equity you cannot afford to hold is equity you may be forced to sell. Positive cash flow reduces financial stress and lets a property pay for itself, so you are not topping up costs from your own wage. That resilience is vital when interest rates rise, and it is the Reserve Bank of Australia cash rate that ultimately sets those repayments. A stronger income buffer is exactly what carries a portfolio through the tougher parts of the cycle, which is why cash flow deserves respect even in a growth-first plan, as our positive cash flow guide explains in detail.
Positive gearing and serviceability
Positive gearing occurs when annual rent exceeds all holding costs, so you make a clear yearly profit. That surplus is taxable, but it makes the property self-sufficient. Cash flow also shapes what you can borrow next, because lenders use rental income to assess serviceability, and a strong yield can be the factor that gets your next loan approved. The tax treatment of income and losses matters here too, which our investment property tax guide covers alongside official Australian Taxation Office guidance.
Boosting the income a property generates
You can actively improve cash flow. Adding a granny flat or secondary dwelling to a large block creates dual income from one property. Cosmetic updates such as a fresh kitchen or paint can command higher weekly rent. Dual-key apartments and co-living setups can also lift gross yield meaningfully. The point is that cash flow is not fixed at purchase; it can be engineered. Even smaller moves add up, from reviewing the rent against the market at each lease renewal to reducing avoidable holding costs such as an overpriced insurance policy or a poorly managed strata scheme. A property that started life mildly negative can often be nudged to neutral or positive through a handful of deliberate decisions in the first year or two of ownership.
Can Renovation Deliver Both Growth and Cash Flow?
Yes, and it is one of the few levers that lifts value and rent at the same time. A well-planned renovation can manufacture equity and improve yield, but a poor one destroys both, so the entire game is choosing upgrades that add more than they cost, or the return on investment that a renovation is supposed to deliver.
Cosmetic versus structural
Cosmetic work improves how a property looks and feels without touching its structure: fresh neutral paint, updated flooring, new tapware and light fittings, and minor kitchen or bathroom refreshes. It is cheaper, faster and usually delivers the best ROI. Structural work, such as extensions, removing walls for open-plan living, or raising a house to build underneath, can add serious value but costs more, takes longer, needs council approval and carries real risk. Kitchens and bathrooms are the rooms that sell homes, and kerb appeal sets the tone the moment a buyer or tenant arrives. In lifestyle markets like the Brisbane property market, knowing which upgrades local buyers actually reward is half the battle.
Avoiding overcapitalisation
Overcapitalisation is the classic trap: spending more on improvements than they add in value. A $50,000 to $100,000 pool may add little in a suburb where pools are not expected, and its maintenance can even deter buyers. The defence is research and numbers, comparing pre and post-renovation values against recent comparable sales, and building a 10 to 20 per cent contingency into the budget for surprises. A disciplined feasibility study and a data-driven approach keep every renovation dollar working, rather than simply adding cost.
Budgeting a renovation by the numbers
A successful renovation is run by the numbers, not by emotion. Material and labour costs have climbed in recent years, and a shortage of skilled trades can stretch both timelines and quotes, so gather several quotes and add a 10 to 20 per cent contingency for the surprises that always appear once walls come off. Track every expense against budget in a simple spreadsheet, and remember to account for professional fees for draftspeople, engineers and council charges. In many markets the sums are tight enough that buying an already-renovated property can beat renovating one yourself, which is exactly the kind of comparison worth running before you commit.
Repairs or renovation before you sell?
If you are preparing a property for sale or re-lease, start with a professional building inspection to surface any structural, plumbing or electrical issues. Addressing genuine faults is non-negotiable, because they deter buyers and invite heavy price reductions. Beyond that, the highest-impact spend is usually the cheapest: kerb appeal through tidy landscaping and a painted fence, and modest updates to the kitchen and bathroom, the two rooms that most influence a decision. The aim is a clean, modern, functional feel that appeals to a broad audience, not an extravagant finish that you will never recover in the price.
Growth First, Cash Flow Later: Finding the Balance
The smartest strategy blends both over a long timeline, and the order matters. Early on, your priority should be building an asset base, because you need equity to fund future purchases. Buying a high-yield, low-growth property first often leaves you stuck: a small weekly profit but no equity to buy again. As the portfolio grows, so does your total debt, which can eventually cap your borrowing. That is the moment to pivot toward higher-yielding assets that service the debt on your earlier growth properties, reducing risk and preparing you for a comfortable retirement.
There is no single moment when this switch flips; it depends on your loan-to-value ratio, your income and your appetite for risk. A useful signal is when your borrowing capacity, rather than your deposit, becomes the constraint on your next purchase. At that point a positively geared property often does more for the portfolio than another growth asset you cannot comfortably hold. Acquire two or three strong growth assets first, then use that equity to add cash flow, and a considered portfolio management approach keeps the sequence on track, with the outcomes visible on our client results page.
What Do the Numbers Show Across Australia?
The market constantly reminds us that growth and yield rarely live in the same postcode. Through 2025 and into 2026, growth has been strongest in tightly supplied capitals, while the highest yields have sat elsewhere. National rental vacancy has hovered around one per cent, according to SQM Research, which keeps upward pressure on rents and supports yields. Darwin and many regional centres regularly offer gross yields above six per cent, whereas capital-city houses more often sit nearer three to four per cent because their higher prices compress the yield.
Underpinning all of it is population, and Australian Bureau of Statistics data confirms the migration that keeps demand firm. The lesson is consistent: chase growth where supply is scarce, and chase yield where prices are low and demand is stable. It is also why a genuinely balanced portfolio often spans more than one city or region, pairing a scarce, growth-oriented capital-city asset with a higher-yielding regional one so neither strategy ever carries all the weight on its own.
How a Buyers Agent Aligns Strategy to Your Goals
Choosing between growth and yield is a sequencing decision, and getting the order wrong is expensive. A premium buyer’s agency engagement starts with strategy, analysing your borrowing power and goals before recommending a single location, then aligning each purchase to your long-term roadmap. That includes the house-versus-unit question our houses or units guide unpacks, since the two behave very differently on growth and yield. Experienced advocates blend market analysis, local research and financial modelling to judge whether a property fits your stage, rather than chasing a headline number.
Frequently Asked Questions
Should I focus on capital growth or cash flow for my first property?
Your first property should usually prioritise capital growth, because it builds the equity needed to fund your second and third purchases. A high-yield property with little growth potential can leave your portfolio stagnant, earning a small weekly profit but never generating the equity required to scale. Growth first, then cash flow, is the common sequence.
Can a property deliver both high growth and high cash flow?
It is rare. Strong growth usually occurs in desirable, expensive locations where yields are compressed, while high yields are typically found in cheaper regional or single-industry towns where growth is more volatile. Most investors aim for a sensible compromise, or manufacture better cash flow through renovation, rather than hunting for a perfect unicorn property.
How does negative gearing help property investors?
Negative gearing occurs when a property’s expenses exceed its rental income, and the Australian Taxation Office lets you deduct that loss against your personal income, reducing your tax bill. It should never be the sole reason to invest, though. Only accept negative gearing when the property is expected to deliver substantial capital growth that outweighs the holding cost.
Which renovations offer the best return on investment?
Cosmetic upgrades typically deliver the highest ROI. Kitchens and bathrooms are the rooms that most influence buyers and tenants, so modest updates there pay off well, along with fresh paint, new flooring and improved kerb appeal. Structural work can add value but costs far more and carries greater risk, so it needs careful feasibility before you commit.
How do I avoid overcapitalising on a renovation?
Research what buyers in your specific suburb actually value, and compare your property’s likely post-renovation value against recent comparable sales before spending. Avoid features that are not standard for the area, such as a high-end pool where pools are not expected, and build a 10 to 20 per cent contingency into your budget so surprises do not erode the gain.
Do buyers agents help with strategy or just finding properties?
A premium buyers agent always starts with strategy, analysing your borrowing capacity and goals before recommending a location or property type. They then align each purchase to your long-term roadmap, balancing growth and cash flow across the portfolio, so the property you buy actually advances your plan rather than simply being available.
Building a Strategic Property Portfolio
Creating wealth through Australian real estate is not luck; it is a disciplined understanding of market cycles, lending policy and asset selection. Capital growth versus cash flow is not an either-or choice, it is a matter of order. Build your equity base first, using high-demand suburbs with strong infrastructure and population growth to do the heavy lifting, then diversify into higher-yielding assets to protect your cash flow and improve your lifestyle.
Renovation, used carefully, can accelerate both. The sooner you set a clear strategy, the sooner you reach genuine financial independence. When you are ready to map it out, a no-obligation strategy consultation is the simplest first step, or you can get in touch with a team that represents only you.
Resources
- CoreLogic: Australian dwelling values and long-term growth data
- SQM Research: rental yields and vacancy rates
- Australian Taxation Office: residential rental property tax rules
- Australian Bureau of Statistics: population and migration
- Reserve Bank of Australia: cash rate and monetary policy
- ASIC MoneySmart: property investment basics
- Investopedia: return on investment explained
Elijah Turkovic is the founder of Amassed, a licensed buyer’s agent in Queensland (licence QPBL 4617660) and a member of the REIQ. He has spent more than 10 years in property, development and real estate, and lives in Broadbeach Waters on the Gold Coast.
He leads the team’s searches, due diligence and negotiations on home and investment purchases across Brisbane, the Gold Coast and the Sunshine Coast. Amassed acts only for buyers and takes no commissions, referral fees or kickbacks from sellers, agents or the inspectors it recommends.