Key Takeaways
A 2026 comparison of beachfront and inland Gold Coast property for buyers and investors weighing capital growth, yield, insurance and risk.
- Beachfront property is scarce and prestigious, but carries high entry prices, salt-air maintenance and rising insurance costs.
- Inland suburbs offer more land, lower holding costs and steady long-term tenant demand for a fraction of the beachfront price.
- The Gold Coast median house price sits near $1.17 million and units around $765,000, so your budget often decides the debate for you.
- Insurance premiums and flood exposure are now central to value, pushing many buyers toward elevated, inland homes.
- The right choice is the one aligned with your goals and risk tolerance, not the postcode with the best view.
The Gold Coast property market has long been synonymous with glittering high-rises and pristine stretches of sand. For decades, the “Australian Dream” here meant securing a spot as close to the ocean as possible. That landscape is shifting. As prices in blue-chip coastal suburbs keep climbing and lifestyle priorities evolve, a real debate has emerged for buyers and investors alike: is the smart money still on the beachfront, or does the opportunity now lie inland? At Amassed, we watch this dilemma play out daily.
Buyers are torn between the emotional pull of the ocean and the practical, often higher-yielding potential of the hinterland and suburban corridors. Making a confident call means looking past the brochure images to the data, the risks and the long-term value drivers of each zone. The Amassed buyer’s agents exist to remove that guesswork, so your decision rests on fundamentals rather than a good photograph.
Is Beachfront Gold Coast Property Still Worth It?
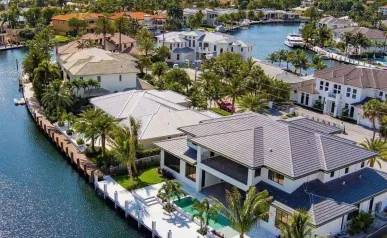
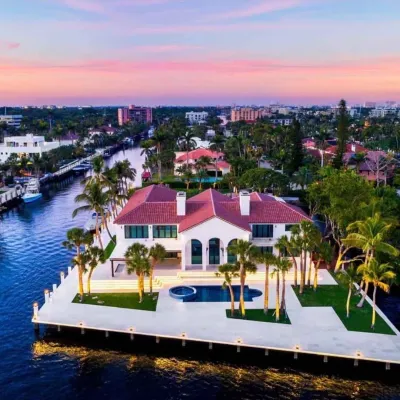
Yes, for the right buyer with the right budget. Beachfront land is finite, and that scarcity underpins its long-term value. We simply are not making any more coastline, which has historically driven strong capital growth in prestige suburbs. Across the wider city, the median house price now sits around $1.17 million, with premium coastal pockets running well beyond that, according to CoreLogic market data. For many buyers, a beachfront home is as much a lifestyle purchase as an investment, and that dual motivation is exactly why the segment holds value through cycles. It is also why a coastal home can anchor a broader Gold Coast real estate investment strategy rather than sit as a one-off purchase.
The advantages of coastal investing
The primary driver is lifestyle appeal. Demand from tourists and interstate migrants remains heavily skewed toward the water, and Queensland continues to lead the nation for interstate migration, per the Australian Bureau of Statistics. Suburbs like Broadbeach and Mermaid Beach offer a walk-to-everywhere lifestyle that commands premium rents. The potential for short-stay holiday income is also significantly higher near the sand, where local rules allow it, giving owners a second income lever that inland homes rarely match.
The risks: insurance, salt air and holding costs
The coastal dream carries a high price tag. Entry costs are substantial, often locking out first-time investors, and the holding costs can be steep. Salt air is corrosive, accelerating wear on buildings and lifting maintenance bills over time. Exposure to storm and flood events also means insurance premiums run higher near the water, a point we cover in detail in our Gold Coast flood risk guide. These ongoing costs quietly eat into net yield, so headline capital growth always needs to be weighed against the true cost of holding the asset year after year.
Why Are Investors Moving Inland on the Gold Coast?
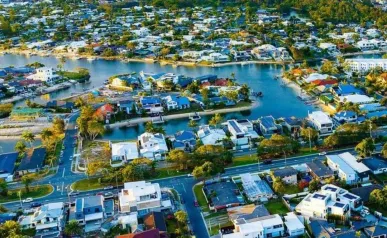
Because the same budget buys far more, with less exposure to coastal risk. As the beachfront strip becomes increasingly exclusive, the “shoulders” of the market and the hinterland are experiencing their own boom. The shift is not only about affordability; it is about space, privacy and community.
More land for your money
Inland suburbs offer significantly more for each dollar spent. You can often secure a large family home on a decent block for the price of a two-bedroom apartment near the beach. The northern growth corridor around Coomera, Pimpama and Nerang provides affordable entry points with strong prospects, driven by major infrastructure and family-friendly amenities. Land content matters here, because over the long run it is the land, not the building, that does the appreciating.
Lower holding costs and steadier yield
Inland homes generally face lower insurance premiums and far less exposure to coastal erosion. Rental yields can be surprisingly strong, with consistent demand from local families and long-term tenants who prioritise schools and quick access to the M1 motorway over beach frontage. That tenant profile tends to be more stable and less seasonal than a holiday-let market, which smooths cash flow and reduces vacancy risk across the year.
The trade-offs of going west
The obvious downsides are the lack of iconic views and a greater reliance on the car. The beach is never far away on the Gold Coast, but inland living usually means driving for most day-to-day activities. Capital growth has historically been steadier and less explosive than prime beachfront land, although that gap is narrowing quickly as the population pushes westward and infrastructure follows.
What this means for first-home buyers
For first-home buyers, the beachfront-versus-inland question is often settled by borrowing capacity rather than preference. Inland houses and outer-corridor townhouses usually offer the only realistic entry into the market, and they come with genuine upside: lower insurance, more land and stable tenant demand if the property later becomes an investment. Buying well in a growth corridor early can build the equity that eventually funds a move closer to the water. The key is not to overreach for a postcode you cannot comfortably hold through rate changes and rising running costs, because a forced sale erases years of gains.
Capital Growth or Rental Yield: Which Should Guide You?
This is the question beneath the beachfront-versus-inland debate. Beachfront leans toward capital growth, where scarce land appreciates strongly but rental returns as a percentage of price are often modest. Inland leans toward yield, where cheaper entry and stable tenants produce healthier cash flow but historically slower growth. Neither is universally better. A high-income buyer building long-term wealth may accept low yield for premium growth, while an investor who needs the rent to cover the mortgage will lean inland. The right answer depends on your income, your borrowing capacity and how long you intend to hold, which is why a clear strategy matters far more than a hot tip about the next boom suburb.
As a rough guide, prime beachfront houses often yield in the low-to-mid 2% range while producing the strongest long-term growth, whereas well-located inland houses and townhouses can return around 4% or more with steadier, if slower, appreciation. Many experienced investors deliberately blend the two across a portfolio, pairing one growth-focused asset with one cash-flow asset, so a single strategy never carries all the risk. That balance is far easier to strike when you separate the emotional appeal of a location from the cold arithmetic of what it will actually earn and cost you to hold.
Are Gold Coast Apartments a Good Investment?
They can be, and for many buyers they are the most realistic way into a premium location. With house prices high, the unit market offers a lower entry point, often from around $560,000 in tourism hubs, against a citywide unit median near $765,000. Beachfront apartments in Surfers Paradise and Broadbeach capture lifestyle demand and short-stay income, while well-chosen units in walkable suburbs deliver reliable long-term rental returns.
The catch is that not all apartments perform equally. Older high-rise stock in oversupplied pockets can see weak capital growth and high body-corporate fees, whereas boutique buildings in scarce, blue-chip locations behave much more like houses in terms of growth. This is exactly the houses-versus-units question that trips up so many investors, and it is worth reading our houses or units breakdown before you commit. The capital growth of a Surfers Paradise unit and a Mermaid Beach house are very different propositions, even though both sit within a few kilometres of the same sand.
Short-stay versus long-term letting
Beachfront apartments open the door to short-stay income, which can lift gross returns in peak season. That upside comes with real costs: higher management fees, furnishing and cleaning, seasonal vacancy and tightening local regulation around holiday letting. Long-term letting is less glamorous but far more predictable, with lower turnover and steadier tenants. Before banking on holiday income, confirm what the body corporate and council actually permit for that specific building, because the rules vary street by street and can change with little notice.
How Insurance and Climate Risk Are Reshaping the Market
Rising insurance is quietly rewriting Gold Coast buying decisions, and it deserves a place in every buyer’s due diligence.
Why premiums are climbing
Premiums in some higher-risk areas have been doubling, according to the Queensland Reconstruction Authority, and the Insurance Council of Australia points to flood and storm exposure as a central driver. As premiums climb, buyers are becoming far more risk-averse, and a clear trend toward “climate resilience” has emerged. Elevated, inland and modern homes built to current standards are commanding stronger demand precisely because their running costs are more predictable.
Doing your flood due diligence
Due diligence now starts with a flood check, not a floor plan. Before making an offer, buyers should review a property against the state’s FloodCheck Queensland maps and the flood overlays published by the City of Gold Coast. Two homes on the same street can sit in very different overlays, and that single difference can swing annual holding costs by thousands of dollars, which flows straight through to resale value and buyer demand later on.
The rise of climate-resilient suburbs
We are also seeing a demographic shift. Younger buyers and families priced out of the beachside are driving gentrification in suburbs like Southport and Robina. These areas are evolving into self-sufficient hubs with their own dining, retail and cultural scenes, reducing the need to travel to the coast at all. For a growing cohort of buyers, resilience and everyday convenience now outrank a water view.
Gold Coast Suburb Snapshot: Where to Look
Understanding the macro trends is useful, but property success comes down to suburb-level selection. Population growth across the city continues to run strongly, as tracked by the Queensland Government Statistician’s Office, which supports demand in both zones. The table below is a starting point, and our Gold Coast suburb guide goes deeper on each pocket.
| Suburb | Profile | Best suited to |
|---|---|---|
| Mermaid Beach | Blue-chip beachfront, house medians well above the city average | Asset security, capital preservation |
| Broadbeach | High-density lifestyle plus luxury homes, strong rental demand | Higher-budget lifestyle investors |
| Southport | The Gold Coast CBD, value pricing near $830,000, light rail | Value buyers wanting infrastructure |
| Surfers Paradise | High-tourism, unit entry from around $560,000 | Short-stay and unit investors |
| Hope Island | Master-planned, golf and deep-water access | Retirees and lifestyle buyers |
| Coomera and Nerang | Northern growth corridor, more affordable land | Families and yield-focused investors |
Blue-chip beachfront
Mermaid Beach and Broadbeach are blue-chip territory and sit among the most expensive suburbs in the Gold Coast. They hold value exceptionally well and suit high-net-worth investors chasing asset security rather than aggressive yield. From a beachfront villa investment to a boutique apartment, scarcity is the entire thesis here, and it is what protects these streets when the wider market softens.
Value and growth corridors
Southport, the city’s CBD, is often overlooked despite its light rail, Broadwater access and comparatively modest medians. Further north, Coomera and Nerang offer affordable land and deep family demand. For a data-led view of where momentum is building next, our best Gold Coast suburbs guide is the place to start before you shortlist.
Which Should You Buy? A Simple Decision Framework
Rather than chasing the “better” zone, work backwards from your own numbers. Start with budget: if beachfront houses are out of reach, the honest choice is a beachfront unit or an inland house, and each behaves differently.
Next, define your primary goal, whether that is long-term capital growth, cash flow today, or a lifestyle home you will eventually live in. Then weigh risk tolerance, including how comfortable you are with insurance costs, body-corporate fees and seasonal income. Finally, fix your time horizon, because scarcity-driven beachfront growth rewards patience, while inland yield supports buyers who need the property to pay its way sooner.
Timing is the final layer. Our Gold Coast market forecast helps frame where the current cycle sits, so you buy with the trend rather than against it. A buyer with a ten-year horizon can afford to look through short-term noise, whereas someone planning to sell within five years should weigh the cycle far more heavily. When those inputs point the same way, the postcode almost chooses itself.
How a Gold Coast Buyers Agent Helps You Choose
Navigating these diverse markets takes more than browsing property apps; it takes a strategic partner who knows the ground.
Local data and off-market access
A leading Gold Coast advocate understands street-level value, flood mapping and zoning changes that an online listing will never reveal. A dedicated buyer’s agency engagement pairs that local knowledge with access to homes that never reach the portals, and you can explore the wider region through our Gold Coast hub. That combination of insight and access is what separates buying on data from buying on emotion.
Negotiation and feasibility
Once the right property appears, disciplined expert negotiation protects you from overpaying in a competitive campaign. For higher-value or development-style purchases, an independent feasibility study stress-tests the numbers before you commit a cent, turning a gut feel into a defensible decision.
Proven outcomes
The value of representation shows up at settlement, not in the brochure. You can see the kind of results this disciplined approach delivers on our client results page, across both coastal and inland purchases.
Frequently Asked Questions
Is beachfront property still a good investment despite rising costs?
Yes, for the right buyer. Beachfront land is finite, which underpins long-term value. Holding costs like insurance and maintenance are higher, but scarcity often drives superior capital growth over 10 to 20 year cycles compared with mass-produced housing estates. It suits buyers with the budget and the patience to hold.
Are Gold Coast apartments a good investment?
They can be. Units offer a lower entry point, often from around $560,000, and strong lifestyle demand near the beach. The key is location and building quality: boutique apartments in scarce, blue-chip suburbs grow well, while older stock in oversupplied pockets can lag and carry high body-corporate fees.
What are the main benefits of buying inland Gold Coast property?
Inland property offers better affordability, larger land sizes and generally lower insurance premiums. Growth-corridor suburbs like Coomera, Nerang and Robina are less reliant on tourism, providing stable rental income from long-term tenants who work in local schools, hospitals and businesses rather than seasonal visitors.
How do rising insurance premiums affect property choices?
Rising premiums are pushing budget-conscious buyers inland. Investors now scrutinise flood maps and construction dates closely. Modern homes in elevated, inland locations are increasingly attractive because they carry lower ongoing holding costs than older, low-lying coastal homes exposed to storm and flood risk.
Is it a good time to buy an apartment on the Gold Coast for investment or personal use?
It depends on the building and suburb, not the calendar. Well-located apartments in scarce, walkable locations continue to attract both tenants and owner-occupiers. Focus on scarcity, body-corporate health and flood exposure rather than trying to time the market, and the same property can serve both purposes well.
Which Gold Coast suburbs hold their value best?
Blue-chip beachfront suburbs such as Mermaid Beach and Broadbeach have historically held value strongly thanks to scarcity and lifestyle demand. Established, well-serviced suburbs like Southport also perform steadily. Value tends to hold best where supply is limited and amenity is high, rather than in oversupplied estates.
Making the Right Call
The choice between beachfront and inland is rarely right or wrong. It is a question of aligning your purchase with your financial goals and risk tolerance. Beachfront offers scarcity, status and capital-growth potential, but demands deep pockets and tolerance for maintenance and insurance. Inland offers affordability, larger land and consistent yields from long-term tenants. By focusing on the fundamentals of supply, demand and liveability, and pressure-testing every option against current data, you can secure a property that performs regardless of its postcode. If you would like that clarity before your next purchase, a no-obligation strategy consultation is the simplest first step, and you can always get in touch with a team that represents only you.
Resources
- CoreLogic: Australian property market data and median prices
- Australian Bureau of Statistics: regional population and interstate migration
- Queensland Government Statistician’s Office: population statistics
- Insurance Council of Australia: home insurance affordability and climate risk
- Queensland Reconstruction Authority: flood resilience and insurance premiums
- FloodCheck Queensland: property flood maps
- City of Gold Coast: local flood overlays and City Plan
Elijah Turkovic
Elijah Turkovic is the founder of Amassed and a leading buyer’s advocate known for helping clients secure high-value properties across Queensland. With a data-driven approach, sharp negotiation skills, and deep market insight, Elijah guides buyers toward smarter decisions and stronger long-term outcomes.